The entry on the liability side is a debit to Lease Expense for $1,749, a debit to Lease Liability for $34,972, and a credit to Cash or AP for $36,721 to record the payment. The entry for the ROU asset is a debit to Lease Expense for $34,972 and a credit to Right-of-use (ROU) Asset for the same amount. Similarly to Year is prepaid rent credit or debit 2, the Year 3 “interest” component is calculated by multiplying the outstanding lease balance of $34,972 by the 5% discount rate, totaling around $1,749. The lease liability reduction and the ROU asset amortization are the difference between the payment and the interest component, which is $34,972 ($36,721 payment – $1,749 “Interest”). The entry on the liability side is a debit to Lease Expense for $3,414, a debit to Lease Liability for $33,307, and a credit to Cash or AP for $36,721 to record the payment.
- Under ASC 842 base rent is included in the establishment of the lease liability and ROU asset.
- It also aids in ensuring that the Generally Accepted Accounting Principles (GAAP) are followed when preparing reports that will be filed with the U.S.
- For the landlord, receiving rent in advance can provide immediate liquidity and financial security.
- The initial recording of prepaid rent involves a double-entry bookkeeping method, which ensures that the financial records are accurate and balanced.
- The IRS generally requires businesses to capitalize and amortize prepaid expenses over the period of benefit, which can affect the timing of deductions.
- It is a common practice in residential and commercial leasing agreements where tenants may pay for several months of rent in advance.
- In contrast, the liabilities of an entity result in a net loss of value.
Helping Businesses and Tenants Avoid Financial Surprises
Finally, prepaid arrangements really strengthen the bond between tenants and landlords. When tenants pay upfront, it demonstrates their commitment and responsibility, building trust that benefits everyone. This positive relationship often results in better care for the property, longer tenancies, and fewer disputes, creating a delightful rental experience for all involved. Moreover, reducing collection efforts means more than just less paperwork. It gives http://www.dsgnoverdose.com/assets-liabilities-and-capital/ property managers the gift of time and resources to pour into impressive tenant services and overall property management, rather than chasing after monthly payments.
- From an accounting perspective, prepaid rent is considered an asset, specifically a current asset, because it represents a future economic benefit for the company that has made the payment.
- This means they are receiving money for services that have not yet been performed for customers.
- Instead, the amount goes into the Prepaid Rent Account on your balance sheet.
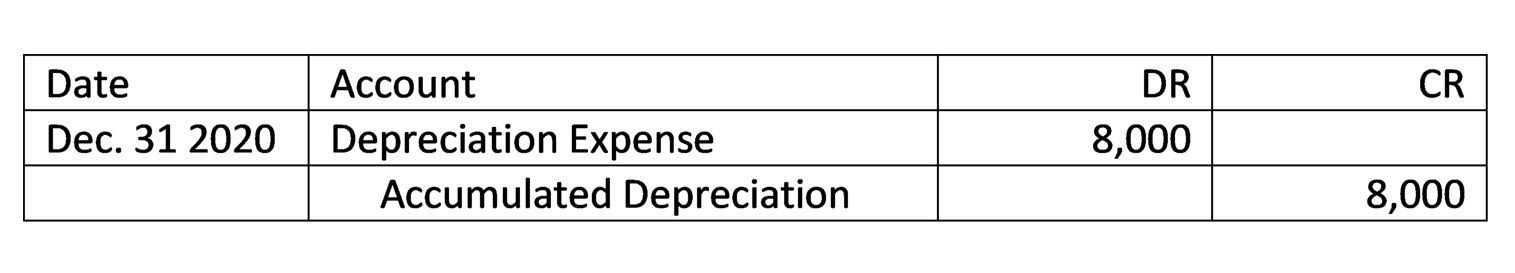
- For instance, if $2,000 of the initial $6,000 prepaid rent expires each month, an adjusting entry would debit Rent Expense for $2,000 and credit Prepaid Rent for $2,000.
- This is particularly important for businesses that need to demonstrate profitability during specific periods.
- For the check to reach the landlord and post by the first, the organization writes the check the week before on the 25th.
Is Prepaid Expense an Asset?
This systematic approach ensures that the financial statements provide a fair and accurate representation of the company's financial position and performance over the lease term. It also aids in budgeting and forecasting, as the expenses are predictable and evenly spread out over the lease period. Understand its classification and the role of debits and credits in its financial representation.
Prepaid Rent as a Deferred Asset
The impact of a debit or credit depends on the type of account involved. They impact the presentation of financial statements, with deferred rent appearing as a liability and prepaid rent appearing as an asset. Both assets and liabilities are recorded in an entity’s balance sheet and represent a company’s financial health snapshot. Similar to fixed rents, the minimum rent is also included in the straight-line rent calculation for operating leases under ASC 840 and the calculation of the lease liability under ASC 842.
Accounting Ratios
- This article will clarify how prepaid rent is treated in accounting, explaining whether it is recorded as a debit or a credit and detailing the complete accounting process.
- The $400,000 you’ve “spent” shows up on your income statement as a rent expense.
- Stakeholders can assess how much cash is tied up in prepayments and evaluate the company’s ability to manage its cash flow effectively.
- Prepaid accounting is the process of paying for expenses in advance before they are incurred or consumed.
How these accounts are treated on the list of financial statements and affect net income depends on whether the rent is being reported for financial reporting or tax purposes. It is a good idea to employ a certified public accountant (CPA) to manage your books and do your taxes, as CPAs are aware of the current accounting rules and tax laws. Since prepaid expenses can only be used up over periodic periods usually less than one year, they are considered current assets rather than non-current assets.
- Similarly to ASC 840, this straight-line lease expense is calculated as the sum of all of the rent payments over the lease term and divided by the total number of periods.
- Black Owl Systems provides a lease accounting software solution that seamlessly aids in this transition, simplifying the application of the lease accounting standards.
- Renting and leasing agreements have existed for a long time and will continue to exist for individuals and businesses.
- The company needs to move the money to the rent expense section as soon as the rental period starts.
- The accrual accounting system is the most prevalent method of accounting used by small businesses and large corporations.
Are Cashier's Checks Certified Funds?
The ROU asset is initially measured as the sum of lease liability, plus any CARES Act initial direct costs and lease payments made before the lease commencement date. Correct classification ensures your balance sheet accurately reflects both assets and liabilities, impacting not only accounting but also financial analysis of your business. When a company initially pays rent in advance, a specific accounting entry is required to reflect the acquisition of this asset. This establishes the asset on the company’s balance sheet, showing the amount of rent that has been paid but not yet consumed.